


Alphabet Drops Below $350: Buying Opportunity or the Start of Something Worse?
Alphabet Drops Below $350: Buying Opportunity or the Start of Something Worse?
Omor Ibne EhsanThu, September 24, 2026 at 5:08 PM UTC
0
JHVEPhoto / iStock Editorial via Getty ImagesQuick Read -
GOOGL fell 3.8% to $337.83 on no company news, leaving a $91 gap to the Wall Street consensus target of $429.
META's Muse AI agent launch pulled rotation away from Alphabet, which trades at a P/E of 18 and holds the lowest valuation among mega-cap AI peers.
Alphabet's $460 billion Cloud backlog supports the bull case, but projected capex near $375 billion and negative free cash flow define the bear risk.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL) closed at $337.83, down 3.8% in the session, while the Wall Street consensus target still sits at $429.46. That is a gap wide enough to matter, and nothing was announced today to explain the move.
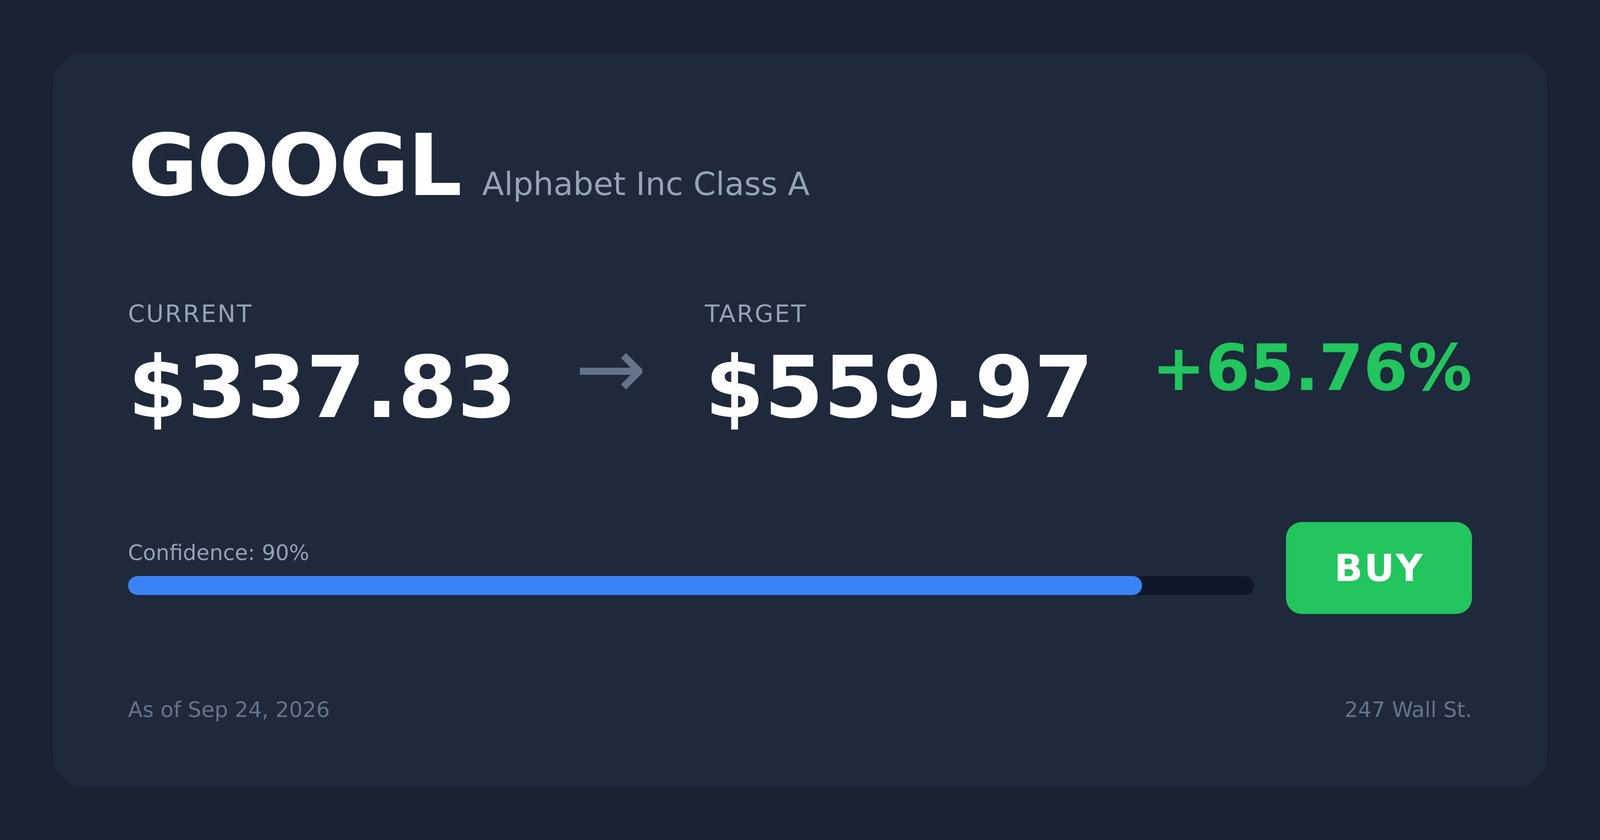
GOOGL Price Target — 24/7 Wall St.
Alphabet runs Search, YouTube, Android, Google Cloud, and Waymo, and it just delivered its eleventh straight EPS beat and twelfth consecutive quarter of double-digit revenue growth. The stock is still up 8.14% year to date and 34.59% over one year.
The tension is about whether the market is starting to charge Alphabet for the cost of its own artificial intelligence buildout, a buildout that also has to be powered, cooled, and networked by somebody, which is the whole subject of our free report on seven AI infrastructure suppliers that aren't chipmakers.
Reporting attributed the drop to rotation into Meta following its Muse artificial intelligence agent launch. A move without a disclosure is a positioning move.
A Selloff With Nothing Behind It
No earnings warning, guidance cut, or regulatory update preceded it. The stock gave back 3.8% in one session.
The last reported quarter looked strong on almost every line. Revenue of $119.8 billion grew 24.23% year over year, and Google Cloud accelerated to 82% growth at $24.8 billion in quarterly revenue.
Capital expenditures hit $44.9 billion in the quarter, up 100.14% year over year, while free cash flow turned negative at -$5.9 billion.
Learn 13 Major Retirement Mistakes and Ways To Avoid Them
One investment mistake could create big risks for your retirement. Many investors make the same critical errors: being too conservative, making big bets on “sure things,” or paying excessive fees. Any of those blunders can endanger your hard-earned savings.
Now you can learn the mistakes even experienced investors make (and ways you can sidestep them before it’s too late) with this new guide: 13 Retirement Mistakes and How to Avoid Them from Fisher Investments. Access your complimentary copy here(sponsor)
Long-term debt roughly doubled from $46.5 billion to $98.2 billion, and the buyback was suspended. Management prioritized compute over shareholder returns.
Why Analysts Have Not Moved Their Targets
The consensus target of $429.46 reflects bullish coverage, with 2 Strong Buy and 1 Buy calls with zero Holds or Sells in Alpha Vantage's sample. 53 analysts contribute to the 2026 EPS estimate.
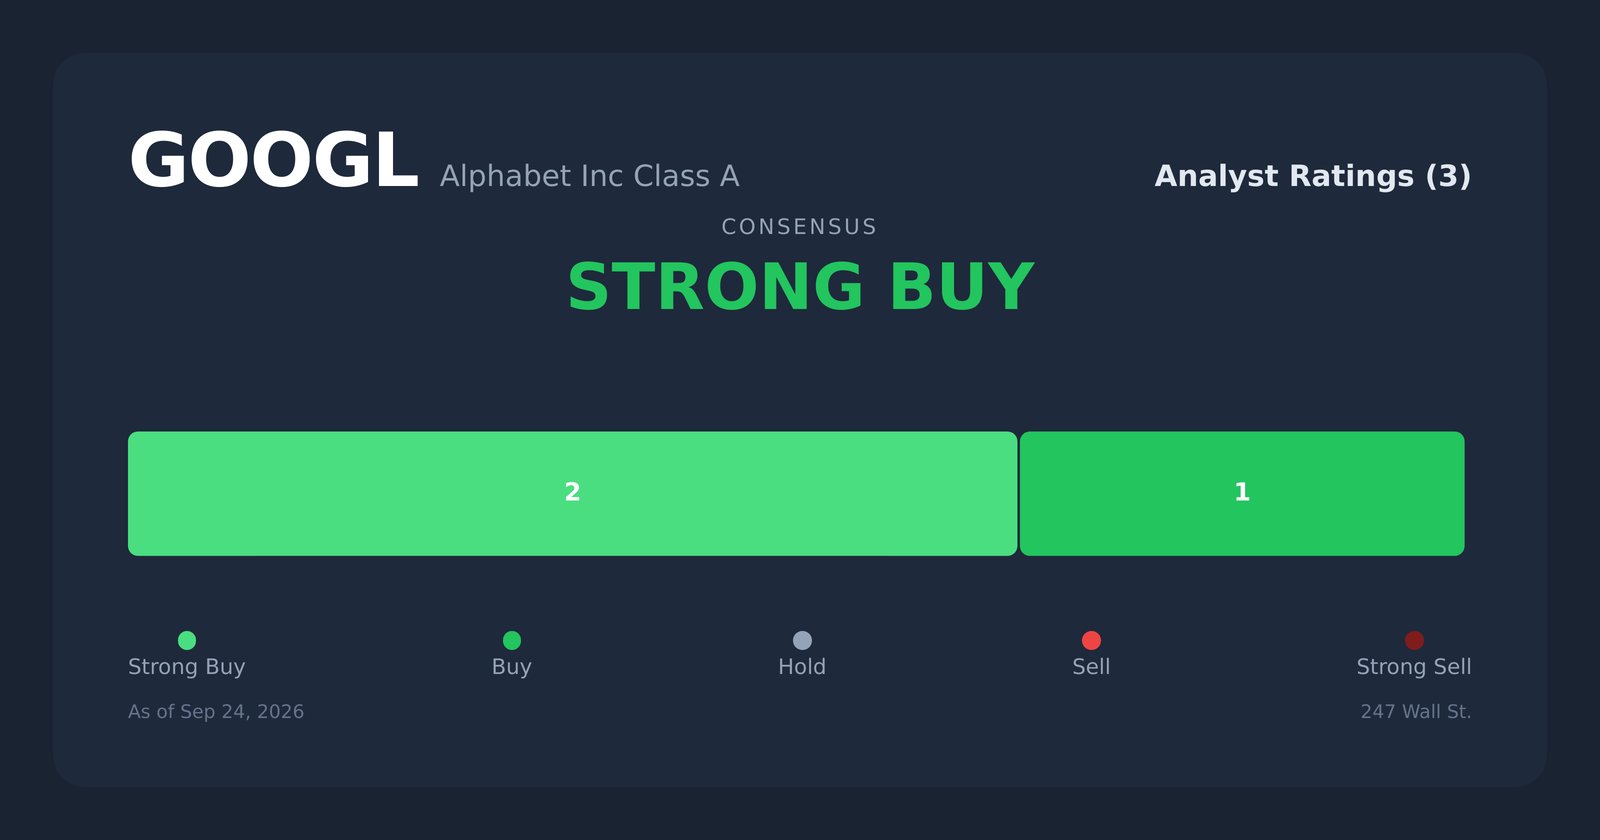
GOOGL Analyst Ratings — 24/7 Wall St.
The bull thesis rests on Cloud conversion. Backlog stood at over $460 billion as of the first-quarter report, up from $155 billion reported for the third quarter of 2025. Backlog is contracted revenue not yet recognized, and it converts only if Alphabet has the compute to serve it.
Advertisement
Consumer artificial intelligence is holding. Nearly 90% of the Fortune 100 use Gemini Enterprise, and the Gemini App has 950 million monthly active users.
The 2026 EPS consensus has climbed from $14.23 ninety days ago to $20.62 currently. Analysts are marking Alphabet up.
Sector peers held up. Money rotated into Meta Platforms (NASDAQ:META) on the day of its Muse artificial intelligence agent launch, while Microsoft (NASDAQ:MSFT) and Amazon (NASDAQ:AMZN) traded on their own catalysts.
Alphabet carries a P/E of 18x and a forward multiple of 23x, the lowest headline valuation among mega-cap artificial intelligence names. The discount reflects the free-cash-flow question rather than market oversight.
Bull and Bear Case for GOOGL Stock
You'd buy Alphabet here if you believe Cloud converts its backlog faster than capex compresses margins. The 82% Cloud growth rate and the $460 billion backlog support that thesis if compute supply keeps arriving.
You'd stay away if the buildout has barely begun. 2026 capex guidance sits at $175 billion to $185 billion, with internal projections reportedly closer to $375 billion.
The equity raise dilutes shareholders. Bond issuance adds interest expense that grew nearly 5x year over year, and the suspended buyback removes support under the stock.
The deciding variable is conversion speed. If Cloud pulls the backlog into revenue at high-double-digit growth for several more quarters, the multiple looks too low. If backlog growth flattens or Gemini cedes consumer ground to Meta's Muse, the market's caution today looks early rather than wrong.
Given demand signals against a shifted balance sheet, I lean cautiously constructive at this level. Free cash flow will decide whether the current multiple is a gift or an accurate warning.
Help Avoid These 13 Retirement Mistakes Before They Derail Your Future
One investment mistake could create big risks for your retirement. Many investors make the same critical errors: being too conservative, making big bets on “sure things,” or paying excessive fees. Any of those blunders can endanger your hard-earned savings.
Now you can learn the mistakes even experienced investors make (and ways you can sidestep them before it’s too late) with this new guide: 13 Retirement Mistakes and How to Avoid Them from Fisher Investments. (sponsor)
Contact editorial@247wallst.com for any questions or corrections.
Source: “AOL Money”
